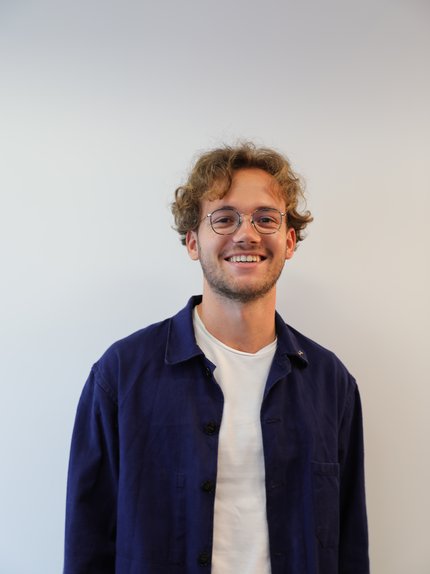
Jules Ducept

Jules Ducept

3rd Year PhD Student

Center for Economics at Paris-Saclay
Paris-Saclay University
Fellow at the International Tax Observatory

Advisors

Jérôme Héricourt
Gabriel Zucman

jules.ducept@psemail.eu

Research Interests

My research interest is in public economics, especially at the intersection of international economics and public finance. I study how cross-border flows and capital allocation are shaped by multinationals' responses to taxation, and their implications for the distribution of taxing rights and for the monitoring of global imbalances. I am particularly interested in building bridges between macro aggregates in national accounting frameworks and novel firm-level data. I also have a continuing interest in political economy, and in particular in the determinants of voting behavior.

Work in Progress

Gender Bias in Voter Mobilization
We estimate the gender penalty faced by women candidates in elections. We exploit the synchronization of French national elections in a difference-in-differences design that overcomes two common identification challenges in the literature: variation in party preferences of voters and strategic allocation of women candidates. Presidential runoffs reveal local partisan preferences in gender-neutral contests, while the subsequent parliamentary races allow us to estimate party-specific gender penalties. Relative to a race between two men, a right-wing woman facing a left-wing man loses 5.2 margin points, against 2.5 for a left-wing woman. We trace these gaps to an asymmetric mobilization channel: the aligned electorate under-mobilizes when their candidate is a woman, while only right-wing voters over-mobilize against an opposing woman. A cross-sectional decomposition attributes part of the penalty to the gender gap in campaign funding, which stems primarily from private donors giving less to women, leaving a residual consistent with biased voter preferences.

Working Papers

ITO Working Paper · DIW Discussion Paper
This paper documents the rise of corporate tax-base narrowing measures in the EU using a novel dataset covering both tax rate and tax base reforms implemented between 2014 and 2022. Our findings indicate a shift away from the 'cut rate – broaden base' approach, as governments increasingly align corporate taxation with industrial policy objectives. We show that EU tax competition exerts downward pressure on high-tax countries, while the likelihood of tax cuts also varies with the political orientation of governments. Using financial accounts from more than 40,000 affiliates, we find that the average effective tax rate of multinational enterprises in the EU has declined more rapidly than the statutory rate and estimate that tax base reforms account for 24% of this decline. The estimated revenue cost of all reforms combined amounts to 3.5% of total corporate tax revenue collected from the sample firms. These revenue losses should be carefully weighed against the anticipated benefits of tax reforms.

Working Papers

with Evangelos Koumanakos and Panayiotis Nicolaides
ITO Working Paper
Using a quasi-experimental setting, we document that corporations decrease declared profits and corporate income taxes in response to an increase in the VAT rate. In an attempt to raise tax revenue during the Greek economic crisis, a 16% VAT rate, which existed for historicopolitical reasons in Greek islands, was harmonised to the national 24% rate. We combine tax filings with Orbis and ICAP data that enable us to geolocate corporations and to construct comparable groups based on locations in or out of the preferential rate. Counteracting the reform's intended effect, declared profits decreased by 28% and corporate income taxes by 34% on a permanent basis. Macroeconomic factors and a fall in reported revenue cannot fully explain this decrease. Pervasive tax evasion in the Greek islands, where corporations might have an opportunity to adjust profits, offers a plausible explanation of the magnitude of responses.

Teaching

Lecturer, International Taxation and Tax Avoidance
Paris Cité University — Masters · Fall 2025
Teaching Assistant, Econometrics
Evry Paris Saclay University — Undergraduates · 2024–2026 · Prof. Jérôme Héricourt
Teaching Assistant, Growth and Business Cycles
Evry Paris Saclay University — Undergraduates · 2024–2026 · Prof. Michel Guillard
Teaching Assistant, International Monetary Economics
Paris 1 Panthéon-Sorbonne University — Undergraduates · Fall 2022 · Prof. Sandra Poncet